Xavier Depouilly, general manager DXL Research & Consulting

The key question shall no longer be how fast Vietnam can grow, but how well that growth can be sustained and shared across businesses, sectors, and the population.

Business sentiment provides an early indication of economic direction. The Business Confidence Index (BCI), conducted by DXL Research for the European Chamber of Commerce in Vietnam, reached 80 points in Q4/2025, returning to pre-pandemic levels.

Around 65 per cent of companies described their current business situation as “good” or “very good”, while 69 per cent expressed a positive outlook for the first quarter of 2026.

Confidence is especially strong among larger companies. Firms with more than 500 employees report even higher optimism, which is significant as these businesses typically invest with a long-term horizon. Their activity supports local suppliers, service providers, and employment, helping strengthen the broader domestic market, including small and medium-sized enterprises.

Meanwhile, tourism was a major contributor to Vietnam’s economic momentum in 2025. Official figures show that more than 21 million international visitors arrived last year, the highest number ever recorded. This recovery supported growth across multiple sectors, including retail, transport, hospitality, and entertainment.

Beyond the main urban centres, tourism has also driven growth in central Vietnam, particularly in Danang and nearby provinces. At the same time, rising incomes are encouraging Vietnamese households to spend more on travel, leisure, and services. This shift towards experience-based consumption is expected to continue in 2026, helping balance the economy and support local businesses.

For many companies, the focus has clearly moved beyond recovery from the pandemic era. BCI survey results show that half of businesses now prioritise business development and diversification, rather than cost reduction. This signals a healthier phase of growth, as firms actively seek new customers, products, and opportunities within Vietnam and in the region.

As we look towards 2026, the roadmap is clear. The World Bank projects growth to moderate slightly to a sustainable 6.3 per cent before accelerating again in 2027, allowing the economy to digest recent gains and focus on efficiency. This growth rate remains strong by international standards and reflects a more stable and sustainable pace.

Elsewhere, technology adoption is becoming increasingly visible across the economy. Around 40 per cent of businesses plan to expand their use of digital tools, automation, or AI. This trend is not limited to large corporations. DXL’s latest consumer research, conducted in December among 900 respondents across four major cities, shows that nearly one in five urban residents already use AI-based tools regularly, mainly for work productivity and information search.

Over time, higher productivity supports wage growth and more sophisticated consumer demand. This creates opportunities not only for technology firms, but also for retailers, service providers, and local brands that can adapt to digital expectations.

Despite these positive signs, 2026 will not be without risks. Vietnam remains exposed to global shocks, including changes in trade patterns and geopolitical tensions. Climate-related risks and supply chain disruptions also remain relevant, as experienced in recent years.

At the same time, internal reforms and administrative adjustments continue to reshape the business environment. These changes are necessary, but they require companies to stay informed and adaptable. Ensuring that growth benefits small businesses, workers, and households will be an important part of building sustainable, inclusive growth.

Vietnam’s outlook for 2026 is encouraging. The foundations for growth are strong, supported by confident businesses, recovering tourism, and evolving domestic demand. The next phase will depend on adaptability, inclusion, and the capacity to manage new external shocks.

For investors and companies, the opportunity is no longer only about producing and exporting from Vietnam, but about growing together with a domestic market that is becoming more digital, more sophisticated, and more demanding.

P5 bài Economy – xuất khẩu hàng hóa ở cảng
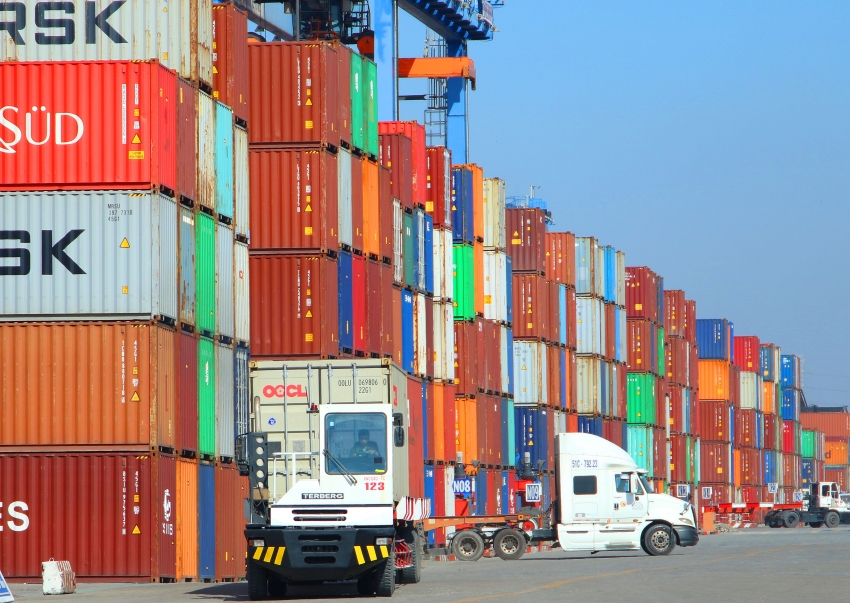
Authorities issued a cautionary notice to help export-import and logistics businesses stay prepared amid evolving global developments. Photo: Le Toan

Official Dispatch No. 229/XNK-TLH, dated March 1, 2026, states that on February 28 marked a serious escalation of tensions in the Middle East and created “serious instability” and posed high risks to transportation activities, international trade and global supply chains.

The agency warned that prices of consumer goods, fuel, and global oil are forecast to rise, generating “indirect and multi-dimensional negative impacts” on Vietnam’s production and export-import activities, as well as on trade with the Middle East.

For logistics services, rising fuel costs are expected to push up sea freight and air cargo rates, particularly on routes connecting Vietnam with countries in the region.

According to the dispatch, several Middle Eastern countries have restricted or closed their airspace due to security concerns, forcing passenger and cargo flights to reroute, prolonging flight times and increasing logistics costs.

Maritime transport has also been significantly affected, as shipping through the Strait of Hormuz has nearly stalled following airstrikes. Iran has warned that passage through the strait is currently unsafe, compelling shipping lines to avoid the area or alter routes, thereby extending transit times and raising fuel expenses.

“Before the above situation, the Agency of Foreign Trade requests export-import industry associations and logistics associations to closely monitor developments,” it said.

Associations are asked to regularly coordinate with relevant state management authorities to provide updates to member enterprises, enabling them to adjust production plans, export-import arrangements, and transport operations.

The agency emphasised the need to “avoid disruptions and minimise negative impacts” from the conflict, while improving flexibility and resilience against fluctuations in the international business environment.

In addition, associations and enterprises are urged to “regularly and proactively analyse and coordinate information” with ministries and relevant agencies regarding trade data, domestic policy changes affecting business operations, cargo flows, freight rates, and surcharges, to prepare appropriate response scenarios for similar situations in the future.

They are also advised to develop preventive and adaptive plans to mitigate risks, losses, and disruptions in international trade and transport activities, and to prepare timely response measures to limit impacts on supply chains.

The dispatch further encourages frequent engagement with relevant MoIT units, including trade promotion and overseas trade offices, to identify new orders and potential markets, thereby formulating alternative or prioritised exploitation plans to “maximise opportunities”.

The agency said that close coordination among associations, enterprises, and authorities would be essential to strengthening resilience and safeguarding Vietnam’s export-import activities amid growing geopolitical uncertainty.

Vietnam making the leap into AI and semiconductors
Csaba Bundik, CEO, CETA Consulting

Crucially, Vietnam’s approach does not seek to compete directly with established global technology leaders in frontier research or advanced chip design. Instead, policymakers and investors recognise that the country’s comparative advantage lies in selective positioning within the AI and semiconductor value chains. In these segments, operational execution, manufacturing discipline, and scalability tend to matter more than being at the technological frontier.

This positioning builds on Vietnam’s existing strengths. The country already benefits from a well-established industrial base in electronics manufacturing and high-tech foreign funding. Global firms have developed large-scale production platforms in Vietnam, creating a dense ecosystem of suppliers, skilled labour, and logistics infrastructure. These capabilities provide a practical foundation for semiconductor-related activities such as assembly, testing, packaging, and advanced electronics manufacturing.

Human capital further reinforces this foundation. Vietnam has steadily expanded its pool of engineers and technology graduates, enabling the development of applied AI solutions, industrial automation, and embedded systems. These technologies are closely aligned with the needs of the real economy, delivering productivity gains across manufacturing, logistics, healthcare, energy management, and public services.

However, the limited availability of senior developers and systems architects with experience in complex, state-of-the-art solutions at scale remains a constraint that will need to be addressed to sustain momentum.

Investor interest is also shaped by Vietnam’s wider external positioning. Political stability, deep integration within ASEAN, and an extensive network of free trade agreements reduce geopolitical and trade-related risks at a time of global supply chain reconfiguration. Reinforced by Vietnam’s “bamboo diplomacy”, these factors support its role as a reliable and politically neutral base for technology manufacturing and deployment. For European backers in particular, this risk profile increasingly supports long-term engagement rather than purely cost-driven decisions.

Such long-term commitments place a premium on policy stability. For deep-tech and semiconductor projects, regulatory predictability consistently outweighs short-term fiscal incentives. Large-scale AI infrastructure and semiconductor investments involve high capital intensity and extended payback periods, making them especially sensitive to regulatory risk.

Vietnam can reinforce confidence by establishing clear and transparent pathways for nationally important technology projects, including streamlined licensing, predictable land-use arrangements, and more effective coordination between central and local authorities.

Within this policy environment, targeted incentives tend to deliver stronger results than broad-based support schemes. Priority areas include semiconductor packaging, testing, and supporting industries; AI computing infrastructure and data centres; and industrial and applied AI solutions aligned with Vietnam’s manufacturing and services base. These segments offer the greatest potential for scale, technology spillovers, and productivity gains while remaining consistent with existing capabilities.

As investment scales up, infrastructure constraints become more visible. Energy reliability has emerged as a decisive factor in technology funding decisions. AI infrastructure and data centres are highly energy-intensive and sensitive to power disruptions, making grid stability, energy availability, and renewable integration strategic enablers of Vietnam’s technology ambitions. Investors increasingly view energy policy as an integral component of the AI and semiconductor funding environment, rather than a separate consideration.

Regulatory credibility also extends beyond energy and investment licensing. Closer alignment with international standards on intellectual property protection, data governance, and AI ethics would further strengthen Vietnam’s standing with global technology corporations. European companies, in particular, operate under strict compliance frameworks and require confidence that intellectual property rights and data security will be enforced in practice. Strengthening implementation capacity, rather than relying solely on formal legal provisions, remains a key priority.

Financing represents another structural constraint. AI infrastructure, data centres, and semiconductor-related projects typically require substantial upfront investment and long payback periods that cannot be fully met through traditional bank lending alone. Vietnam has scope to combine state leadership, market mechanisms, and international capital into a balanced model suited to deep-tech development.

A practical financing framework could include long-term institutional capital and project finance for AI infrastructure and data centres; growth equity and venture capital to scale AI-enabled industrial technologies; and public–private co-funding mechanisms to reduce early-stage risk and crowd in private capital. Targeted tax incentives for technology companies, venture capital funds, and angel investors can further support ecosystem development. The central objective is to mobilise patient capital that supports long-term capability building rather than short-term returns.

Experience from Europe highlights the importance of ecosystem design. Successful innovation systems connect research, scale-up, manufacturing, and market access rather than treating them as isolated stages. Mission-driven innovation drives help align public funding with clear national and industrial priorities, ensuring that technological development addresses concrete economic needs.

Vietnam can accelerate the development of its AI and semiconductor ecosystem by strengthening university–industry collaboration, promoting cross-border research and development partnerships that facilitate knowledge transfer, and developing technology clusters linked to existing manufacturing and logistics strengths. Encouraging technology owners to establish regional or Asian headquarters in Vietnam would further enhance technology diffusion and managerial spillovers.

International cooperation should extend beyond technology transfer to include human capital development, institutional learning, and long-term competitiveness. Fast-track immigration and work permit procedures for highly skilled technology professionals and venture capital experts, alongside stronger enforcement of intellectual property protection, would help sustain confidence.

Looking back at 2025, how would you assess the journey the finance sector has gone through?

In 2025, despite numerous challenges, under the sound leadership of Party General Secretary To Lam, the Politburo, the Party Central Committee, and the National Assembly, and also under the drastic direction of the government and the prime minister, our country has reaped comprehensive outcomes across all sectors.
Entire financial sector steps firmly into a new spring
Minister of Finance Nguyen Van Thang

Within this overall success, the financial sector made important contributions with many notable achievements.

The entire sector upheld solidarity, responsibility, and creativity, ensuring the smooth operation of the newly reorganised apparatus while fully delivering on tasks related to state finance and budget management, investment, and socioeconomic development.

Requirements were increasingly demanding, while the organisational structure was undergoing consolidation and streamlining. In response, the Ministry of Finance (MoF) thoroughly implemented the principles of discipline, accountability, efficiency, and acceleration, rolling out tasks in a coordinated manner across all areas.

The ministry advised the Politburo on issuing a resolution on private sector development; submitted 28 laws and resolutions for approval; proposed 86 decrees and resolutions to the government; and issued 144 circulars, accounting for around one-quarter of all legal normative documents approved nationwide during the year.

These regulations not only addressed economic obstructions but also established legal frameworks for emerging and complex areas such as science and technology development, innovation, and digital transformation; the establishment of an international financial centre; and the formation of new financial markets and products, including digital assets.

Fiscal policy was managed in a targeted expansionary manner, closely and effectively coordinated with monetary and other macroeconomic policies to stabilise the macroeconomy, control inflation, safeguard major economic balances, and lay a solid foundation for growth.

Administrative reform continued to accelerate, with public services modernised to improve the business and investment climate and create maximum convenience for citizens and enterprises.

At the same time, the financial sector implemented various measures to unlock resources for development investment and successfully upgraded the stock market, expanding market scale and attracting foreign capital linked to science and technology development. These results added bright highlights to Vietnam’s fiscal landscape in the final year of the term and created strong confidence heading into a new development phase.

State budget revenue was a particular bright spot in 2025. Could you elaborate?

State budget revenues last year reached the highest level ever. Total revenues amounted to approximately $106.6 billion, exceeding the estimate by 35.53 per cent, despite the implementation of large-scale tax and fee exemptions, reductions, and deferrals worth nearly $10 billion to support businesses and households.

This performance reflects the resilience and recovery capacity of the economy, as well as the effectiveness of revenue management, base broadening, and revenue nurturing, alongside positive impacts from digital transformation in public finance.

More importantly, the revenue structure has become increasingly sustainable, driven mainly by production and business activities. This provides a critical foundation for safeguarding national financial security and creating fiscal space for development objectives in the coming years.

On the expenditure side, the state budget prioritised development investment. The PM assigned a record public investment plan exceeding $44 billion for 2025, helping to crowd in private investment and open new growth spaces. Cumulative expenditure for the year is estimated at $97 billion, equivalent to 94.1 per cent of the budget estimate.

Higher revenues and spending savings were mobilised, for example, to fund boarding schools for students in remote and disadvantaged areas, cover costs arising from organisational restructuring from central to local levels, promptly address disaster recovery, and meet other urgent needs.

Ultimately, these figures all serve a single objective: putting people at the centre, safeguarding social welfare, and advancing sustainable development.

There has also been an unprecedented organisational restructuring in the financial sector. How did this affect governance and operations?

The consolidation and merger of agencies was a major decision with long-term strategic significance. Initial implementation inevitably posed challenges, as the new apparatus had to operate while being refined, amid an expanding workload.

However, thanks to close guidance from the Party, state, government, and prime minister, and the strong sense of responsibility across the sector, the new organisational structure quickly stabilised and operated smoothly, without disrupting financial and budgetary management.

Over the longer term, organisational restructuring and streamlining will enable the finance sector to enhance its effectiveness and efficiency, while strengthening coherence and unity in policy advice and the management of fiscal-budgetary policy, investment, and socioeconomic development. This also represents a critical preparatory step for the sector to meet higher development demands in the coming period, as the economy continues to expand in scale and complexity.

The financial sector has been tasked with implementing multiple major Party resolutions that require substantial resources. How will the MoF balance development goals with fiscal discipline?

The simultaneous rollout of multiple major Party resolutions within a single period places exceptionally high demands on the management of public finance and the state budget. At the same time, it presents a critical opportunity for the MoF to fundamentally reshape its approach to resource allocation, towards greater efficiency, sustainability, and clear strategic focus.

The ministry adheres to the principle of aligning budget management with medium- and long-term development goals, maintaining fiscal discipline and public debt safety while retaining flexibility to prioritise strategic tasks identified by the Party.

The MoF will continue to restructure the state budget by increasing the share of development investment, rigorously curbing recurrent expenditure, and enhancing the efficiency of every unit of public capital. In this framework, the state budget will act as catalytic capital, concentrating on strategic areas, thereby crowding in and mobilising maximum social resources, particularly from the private sector, foreign investors, and other legitimate funding sources.

In parallel, the financial sector will further refine the fiscal and budgetary institutional framework towards greater transparency and disclosure, strengthen decentralisation and delegation, and develop financial markets in a more synchronised manner to diversify funding channels for the economy, easing pressure on the state budget. Revenue administration will also be intensified through broadening the tax base, preventing revenue leakage, and nurturing sustainable sources of income, thereby creating fiscal space for the effective implementation of the Party’s and state’s major policy priorities.

Entering the first year of the 2026-2030 term, what are the sector’s key priorities to realise the goals set by the 14th National Party Congress?

The MoF will focus on six priority task groups. Firstly, it will effectively implement the resolution of the 14th National Party Congress and advise on the timely issuance of all guiding documents for newly adopted laws and resolutions, targeting completion by the first quarter of 2026 in line with the Party general secretary’s directive, so that Party policies can be brought into practice swiftly and effectively.

Secondly, the MoF will fully institutionalise and implement Party resolutions on developing all economic sectors, accelerate the restructuring of governance and capital at state-owned enterprises, and improve operational and investment efficiency to reinforce the role of the state economy.

At the same time, it will foster the private sector as a key growth engine, expand markets for the collective economy and cooperatives, and engage and deploy foreign investment more effectively, thereby strengthening growth foundations and enhancing economic resilience and competitiveness.

Thirdly, it will continue to pursue a targeted expansionary fiscal policy, closely coordinated with monetary and other macroeconomic policies to support high growth while safeguarding national financial security and macroeconomic stability. Public investment will be restructured for greater efficiency, with resources prioritised for projects that reshape development space and momentum, guided by strict economic efficiency criteria.

Fourthly, we will advance the development of a modern, transparent, and integrated stock market as a primary channel for medium- and long-term capital mobilisation, while attracting international investment funds. It will also refine the legal framework for new economic models and financial products, including the knowledge and circular economies, carbon markets, green bonds, and digital assets.

Fifthly, policies will be regularly reviewed and assessed for effectiveness, with institutional and procedural impediments decisively removed. Integrated, long-term planning will be strengthened alongside regional and sectoral links, comprehensive digitalisation of financial public services, and the streamlining of administrative procedures. This will foster a transparent and competitive environment and help form new growth poles, key economic zones, and special economic zones with regional and global competitiveness.

Sixthly, policy communication will be further intensified through stronger dissemination and enforcement of laws and regulations, building broad consensus among the public and business community, and ensuring close alignment between lawmaking and law enforcement, with greater discipline and accountability in policy implementation.
Azmi Bin Wan Hussin Wan, chief operations officer CT Semiconductor

However, for global semiconductor corporations, interest or policy declarations alone are insufficient. Capital flows are only truly activated when concrete, verifiable, and operationally effective trigger conditions are met.

Global semiconductor investors do not make decisions based on potential or paper-based strategies. They invest in countries where operational conditions have been demonstrably proven.

The first decisive criterion is industrial infrastructure reliability. Semiconductor manufacturing requires uninterrupted power supply, ultra-pure water, stable operating environments, full ecosystem for supply chain, and logistics systems capable of withstanding disruptions.

Investors assess not only installed capacity, but also redundancy and continuity of operations. Without proven industrial-grade reliability at this level, Vietnam is unlikely to become a priority destination.

The second criterion is long-term policy predictability and credibility. Semiconductor investments typically have very long lifecycles. As such, confidence in the stability, transparency, and consistency of legal frameworks, government policy including tax, import/export, land-use rights, and investment procedures is more critical than the level of incentives offered.

From my perspective, domestic enterprises play an anchoring role in building market confidence. By committing long-term capital and aligning closely with national priorities, such as Vietnam’s semiconductor industry development strategy to 2030, Vietnam’s direction is structural rather than short-term.

The third criterion is scalable human capital. Beyond highly skilled engineers, the semiconductor industry requires large numbers of process engineers, technicians, and skilled operators. Vietnam’s competitiveness will depend on its ability to rapidly scale this workforce in both quantity and quality.

Compared with Malaysia, Indonesia, and India, CT Semiconductor identifies Vietnam’s greatest weakness as its limited participation in the semiconductor value chain, particularly in advanced manufacturing and outsourced semiconductor assembly and test (OSAT).

Malaysia has built a mature OSAT ecosystem over several decades, supported by dense supplier and service networks. India, while still developing, has mobilised substantial state resources under a clear national strategy. Vietnam, despite its strong electronics manufacturing base, lacks hands-on experience in large-scale semiconductor production operations.

However, human capital and supporting services are areas where Vietnam can improve most rapidly if approached correctly. The key lies in sustained collaboration among three pillars: government, academia, and industry, where training must be closely linked to practice and real production environments.

In this context, CT Semiconductor has implemented a programme on assembly, testing, and packaging (ATP) at the National Innovation Centre in Hanoi. Delivered by international experts with over 30 years of industry experience and fully funded by the company, the programme attracted 180 lecturers from more than 50 universities and colleges nationwide, forming the core teaching force for Vietnam’s future semiconductor engineers.

Vietnam should adopt a phased development strategy, rather than attempting to cover the entire ecosystem from the outset. ATP should be the initial priority: this segment requires significantly lower capital investment than wafer fabrication, offers faster deployment timelines, and aligns well with Vietnam’s existing electronics manufacturing base. ATP facilities also generate immediate demand for materials, chemicals, equipment maintenance, and logistics, catalysing the formation of a supporting ecosystem.

Chip design capabilities can be developed in parallel, particularly in areas such as power electronics, automotive chips, and AI applications. However, design alone is insufficient to anchor supply chains. Physical manufacturing assets, especially ATP plants, create long-term commitments and stronger economic spillover effects.

On the next move, Vietnam can gradually expand into materials, equipment services, and eventually wafer fabrication as conditions mature. Based on this trajectory, we are working towards building a fully integrated semiconductor ecosystem, mastering the entire process from research and training to design, lithography, assembly, testing, and advanced packaging.

We believe several non-financial factors will become increasingly decisive in the coming years. Foremost among them is policy consistency and institutional coordination between central and local authorities, particularly in taxation, customs, and administrative procedures.

Intellectual property protection is another critical factor, especially as advanced packaging technologies and design intellectual property continue to rise in value.

Environmental, social, and governance (ESG) compliance has also become a strategic requirement. We are committed to fully complying with international ESG standards to meet the growing expectations of global partners.

Finally, connectivity with the global ecosystem, through trade agreements, mobility of international experts, data governance frameworks, and alignment with global technology standards, will strongly influence decisions.

We identify three key criteria to activate a new wave of semiconductor investment into Vietnam during the next five years: a long-term national semiconductor strategy with binding commitments; development of ready-to-operate semiconductor industrial zones, with guaranteed infrastructure and streamlined licensing procedures; and large-scale development of technical human capital, focusing on application-oriented engineers trained in collaboration with industry.

If Vietnam can translate these criteria into tangible capabilities rather than policy aspirations, the country will not only draw in funding, but progressively position itself as a strategic node in the global semiconductor supply chain, anchored by pioneering enterprises already turning these conditions into reality.

Vietnam has set ambitious goals for AI and big data under its digital government roadmap to 2030. From your experience, what are the main challenges in turning these goals into real, working geospatial and AI systems?

Digital security fundamental for better and faster decision-making
Abhay Swarup Mittal

The strategic direction set by the government is very strong and closely aligned with global trends. Across many countries, geospatial data has moved beyond being a supporting layer of infrastructure. It has become a daily operational requirement for governments.

Geospatial data is used constantly by transport systems, delivery platforms, urban services, and many other applications. This widespread usage creates a need for continuously updated data. Satellite and space-based data are the most effective tools for meeting this requirement, as they provide up-to-date information on changes to buildings, land, and infrastructure.

However, extracting value from satellite data requires more than access to imagery. A robust infrastructure is needed to process and analyse large volumes of data. Equally important is a regulatory framework that allows such data to be used securely and responsibly.

Vietnam already has a strong talent base, particularly in AI and software development, which can support automation and large-scale data processing. The remaining challenge lies in governance, putting in place the right infrastructure, standards and regulatory environment.

Climate risks such as flooding and rapid urban growth are major concerns for Vietnam. How are government agencies using satellites and geospatial data today, and how has this changed in recent years?

Five years ago, monitoring floods and other climate-related events was far more difficult. Climate change has increased both the frequency and unpredictability of such events, while access to satellite data was often delayed by several days. In disaster situations, that delay significantly limited the ability to respond effectively.

Today, the situation has changed considerably. A growing number of earth-observation satellites are now in orbit, enabling access to data within hours rather than days. This shift has transformed how governments approach disaster management.

Near-real-time satellite data supports more informed decision-making. Authorities can assess the extent and direction of flooding, identify vulnerable areas and prioritise the deployment of emergency personnel and resources.

The ability to predict how floodwaters are moving allows governments to move from reactive to proactive responses. This is a major step forward in building resilience against climate-related risks.

Many countries still depend on foreign platforms for satellite imagery and data analysis. Why is it important for governments like Vietnam’s to build their own capability to receive and analyse earth-observation data?

Sovereign systems have become increasingly important because data is central to modern governance. Governments manage vast amounts of information, including population data, infrastructure data and connectivity data, all of which are used to support public decision-making.

Satellite imagery related to disasters is only one part of a much broader ecosystem. When combined with other national datasets, geospatial information becomes more powerful. In this context, ownership and control over data and infrastructure are critical.

Building sovereign capability does not only mean owning satellites. It also involves owning the ground infrastructure, the data platforms and the analytical systems that turn raw data into actionable intelligence. When these elements are controlled domestically, governments are better positioned to address national priorities.

Vietnam is a growing technology development hub. How does Aetosky’s software development work in Vietnam support its projects and cooperation with local partners?

Vietnam’s development over the past three decades has been remarkable. The depth of technical talent and the strong commitment to skills development stand out clearly.

Vietnam is not viewed as an outsourcing destination, but as an integral development centre. The quality of technology and engineering talent is comparable to that found in leading global companies. The key lies in identifying the right people, investing in their development and establishing a clear execution strategy.

While ideas are abundant, execution ultimately determines success. With a defined strategy and disciplined implementation, Vietnam’s technology workforce can play a central role in developing and deploying advanced geospatial and AI solutions.

How does AI help public agencies make better decisions based on geospatial data in areas such as urban planning, land management, and infrastructure?

AI is essential for automating complex processes at scale. In rapidly developing environments, changes are seen daily, making manual monitoring impractical.

One important application is change detection. By combining satellite imagery with AI models, it becomes possible to automatically identify what has changed in a given area, new construction, land-use changes or unauthorised developments. This approach is already being applied in other countries to support urban planning and regulatory enforcement.

Early detection enables authorities to take timely action, preventing issues such as encroachment before they escalate into legal or social challenges. More broadly, AI supports continuous monitoring, mapping and decision-making, allowing public agencies to act proactively rather than reactively.

Data security and control are common concerns when governments adopt AI technologies. How does Aetosky address these issues?

Data security is fundamental. Building secure systems requires sustained effort, and this is something that cannot be compromised. Strong governance frameworks must be embedded into system design from the outset.

Aetosky places significant emphasis on data protection, ensuring that platforms meet strict security and governance standards. Systems are designed to operate securely and undergo approval processes that align with government requirements.

Which areas are likely to benefit most from geospatial data and AI in Vietnam, and how does Aetosky plan to expand its operations in the country?

Defence and security remain major drivers of earth-observation data globally. Alongside this, disaster response is expected to see particularly strong growth, as it directly affects public safety and livelihoods.

Disasters take many forms like floods, typhoons, landslides, earthquakes, and their impacts are often concentrated in urban areas, where population density is high. Urban resilience therefore becomes a critical focus area, linking disaster management with city planning and infrastructure development.

Agriculture and border management also benefit from geospatial intelligence, but their dynamics differ. Disasters are highly dynamic events, requiring real-time insights and rapid response, which places them at the forefront of demand for advanced geospatial AI.

Aetosky is in the process of establishing an office in Vietnam and expects to begin operations in the coming months. As foreign investment and urbanisation accelerates, the need for robust geospatial and AI systems will grow.

With Vietnam launching its own satellites and expanding its various space capabilities, collaboration with public agencies is expected to deepen, supporting the development of sovereign, data-driven solutions tailored to national priorities.

Why has resilience become such a crucial benchmark for businesses today?

Businesses around the world are operating in a very different environment than even a few years ago. We’re facing global uncertainties, supply chain disruptions, rising energy demands, and more frequent climate related challenges.

Resilience as new benchmark for smarter infrastructure
Dr. Pham Thai Lai

Here in Vietnam, 2025 was a stark reminder of this reality, with the country experiencing a series of severe natural disasters, from prolonged heatwaves and record–breaking storms to widespread flooding that disrupted industries, logistics networks, and daily life. These events made it clear that external shocks are no longer rare; they are becoming part of the operating landscape.

Efficiency still matters – it always will – but efficiency alone is no longer enough. Companies now need resilience, meaning the ability to anticipate disruption, withstand shocks, and recover quickly while keeping operations stable. What is especially important is that resilience and decarbonisation are no longer opposing forces – they actually reinforce one another.

If you think about it, a system that is cleaner, more flexible, and more distributed is also less vulnerable to single point failures. Decarbonised systems tend to be electrified, decentralised, and digitally enabled. Those are precisely the characteristics of resilient infrastructure.

The common foundation that enables both resilience and sustainability is digitalisation. Digital technologies give us transparency, speed, and precision. They allow systems to sense conditions in real time, respond dynamically, and adapt proactively. Without digitalisation, neither resilience nor decarbonisation can advance at the speed the world requires.

Electrification plays a major role in decarbonisation. What challenges does it create for current infrastructure?

Electrification is the most widely accepted and practical pathway towards a net zero future. It is proven, scalable, and applicable across sectors – from manufacturing and transportation to buildings and logistics. In our global Infrastructure Transition Monitor, 64 per cent of leaders agreed that electrification is the most realistic route to net-zero.

But electrification also adds complexity. When companies adopt electric vehicles, electrified machinery, heat pumps, or rooftop solar, they introduce new loads and variable two way power flows. The grid must handle unpredictable peaks, integrate distributed energy sources, and stay stable even as usage patterns shift quickly.

Many grids, globally and across ASEAN, were not built for this level of variability. That is why infrastructure is often cited as the biggest barrier to meeting sustainability targets. The challenge is not ambition; it’s system readiness.

To move forward, we must make infrastructure smarter, not just bigger. Digital grid software, smart transformers, intelligent switching devices, and automated controls give operators real time visibility and better control. These tools help balance loads, reroute power, prevent congestion, and integrate renewables more efficiently. This is how we build a grid that is both electrified and resilient.

Where does digitalisation, and especially AI, fit into building resilient energy systems?

Digitalisation is the engine of resilience. It turns rigid, analogue systems into intelligent networks that can sense, predict, and respond instantly. But it only works when organisations have access to the right data. Many still struggle with data gaps, siloed systems, or limited analytical capabilities, making decarbonisation harder.

This is where AI makes a real difference. Two thirds of leaders in our research believe AI will transform infrastructure operations, and we already see it happening. AI can forecast demand spikes, detect anomalies, and warn operators about potential failures long before they escalate. In regions facing extreme weather or rapid growth, these capabilities can prevent outages and strengthen system stability.

To support this shift, Siemens developed the Industrial Copilot, a generative AI assistant for the entire industrial value chain. It helps generate automation code, assists with troubleshooting, speeds up maintenance planning, and simplifies knowledge transfer. Work that once took days can now be completed in minutes, reducing effort and error rates.

By combining AI with real time operational data, companies move from reactive management to proactive optimisation. This dramatically boosts resilience because systems can adjust automatically and intelligently – even before human intervention is needed.

Siemens recently announced an expanded AI partnership. What does this mean in practical terms for customers and resilience?

Our expanded partnership with Nvidia is about bringing AI into every stage of the industrial value chain. Together, we’re building an Industrial AI operating system to help companies innovate faster, optimise continuously, and operate more resiliently.

Practically, this means three things. First, we are delivering AI accelerated tools – from electronic design to simulation and adaptive manufacturing – allowing faster, more accurate engineering and real time optimisation.

Second, we are enabling an “AI Brain” for factories. By combining Siemens automation and operations software with Nvidia’s AI and simulation platforms, factories can analyse digital twins continuously and convert insights into action on the shop floor. The Siemens Electronics Factory in Erlangen will be the first blueprint, and companies like Foxconn and PepsiCo are already evaluating these capabilities.

Third, we are accelerating GPU powered engineering and AI physics models. This allows autonomous digital twins and 2-10× faster design workflows, improving both reliability and speed.

For customers, the benefits are clear: faster design cycles, shorter commissioning, more reliable operations, and stronger resilience through AI driven prediction and autonomy.

What does all this mean for Vietnam, and what must the country focus on in the coming decade?

Vietnam stands at an important turning point. Its economy is expanding rapidly, its manufacturing base is growing, and its energy demand continues to rise. At the same time, the country remains one of the most climate exposed in Asia, which makes the need for resilient infrastructure more urgent than ever.

Digitalisation gives Vietnam a tremendous advantage. Instead of following a linear development path, Vietnam can leapfrog older models and adopt modern technologies from the outset. Smart grids, AI enabled platforms, digital twins, and AI-driven engineering tools – like Industrial Copilot – allow us to plan more precisely, operate more efficiently, and adapt to change more effectively.

With strong renewable energy potential and a clear national commitment to sustainability, Vietnam is well positioned to become a regional leader in smart infrastructure. But to achieve this, resilience must become the new benchmark – not just a target, but a guiding principle for how we design, build, and operate our energy and industrial systems. If we embrace that mindset, Vietnam can secure a cleaner, stronger, and more stable future for decades to come.

As global conditions continue to shift, resilience is the new benchmark for smart infrastructure. Electrification, digitalisation, and AI are reshaping how systems are designed, operated, and future proofed. For businesses across ASEAN and for nations like Vietnam, those who prioritise resilience today will be best positioned to grow sustainably, adapt quickly, and thrive in an increasingly dynamic world.

At last week’s Singapore Airshow 2026, Vietnam emerged as a focal point in conversations about Asia’s next aviation growth frontier.

Two aircraft manufacturers, business jet provider Dassault Aviation and the world’s largest turboprop manufacturer ATR, arrived with a shared message: Vietnam’s aviation market is expanding rapidly, but its next phase of development will depend on filling structural gaps rather than adding more capacity on already crowded routes.

Aircraft makers urge out-the-box thinking

Vietnam’s business aviation market remains small by regional standards, but Dassault Aviation sees clear momentum building. According to Carlos Brana, executive vice president for Civil Aircraft at Dassault, the growth trajectory mirrors patterns seen previously in other emerging Asian economies.

“Vietnam’s business aviation market is still young, but it is developing quickly,” Brana said. “Vietnam’s strong economic expansion, underpinned by industrialisation and deeper integration into global supply chains, is creating new mobility needs for companies operating across borders. As enterprises scale up, the limitations of scheduled airline networks become more apparent.”

The fundamental value proposition, he stressed, is time efficiency. Direct point-to-point travel between secondary cities can eliminate multiple stopovers, enabling companies to reach destinations that are poorly served or not served at all.

While Vietnam’s fleet of business jets remains modest compared with markets such as Singapore, Thailand or Indonesia, Dassault expects steady growth over the next 5-10 years as economic activity becomes more geographically dispersed.

Vietnam’s ongoing airport expansion is often cited as a constraint, but Dassault argues that business aviation is well-suited to operate within existing infrastructure. Business jets can operate from airports closer to final destinations, reinforcing their time-saving advantage. In many countries, including France, smaller airports rely heavily on business aviation to sustain operations, an experience Vietnam could replicate as its regional airport network expands.

While business aviation addresses a niche segment, ATR sees a much larger structural gap in Vietnam’s aviation ecosystem: the near absence of regional turboprop operations. Despite rapid traffic growth, turboprops – typically a hybrid aircraft engine that uses a gas turbine to drive a propeller – account for about 2 per cent of Vietnam’s commercial fleet.

Jean-Pierre Clercin, managing director and head of Asia-Pacific at ATR, said, “Vietnam’s aviation growth has concentrated on long-haul and high-density routes, north-south travel and international connectivity within ASEAN and beyond. For those markets, jets are the most efficient solution.”

That strategy has delivered impressive results, but it has also concentrated traffic heavily at a small number of airports. ATR research shows that roughly 90 per cent of Vietnam’s air traffic flows through just 10 airports, placing increasing pressure on major hubs.

“Smaller cities and secondary regions are growing economically, and residents increasingly aspire to move faster and more efficiently, not only by road but by air,” he added.

Turboprops, designed for short stage lengths and thinner routes, are well-suited to this next phase. ATR aircraft typically operate most efficiently on flights of around one hour, routes that are often unviable for jets due to cost structures.

Currently, Vietnam has approximately 22 operational civil airports. Of these, about 11 are international airports, and 11 are domestic airports. According to Vietnam’s national airport plan, Vietnam aims to expand its airport network to as many as 33 airports by 2030. Most recently, the Long Thanh International Airport, which underwent technical opening in late 2025, is expected to begin commercial operations in mid-2026.

ATR argues that the development of regional aviation is not just about domestic connectivity. Short-haul international routes linking Vietnam with neighbouring countries also offer strong opportunities, thanks to turboprop aircraft.

“The need for a thinner, more granular network will become unavoidable. This would help ease congestion at major hubs while making better use of investments in regional airports,” Clercin said.

“Policy support will be critical. Simplifying regulations for smaller airlines, reducing entry barriers and offering incentives such as lower airport fees on secondary routes could encourage new regional carriers to emerge. If the operating environment supports profitability, new regional airlines will follow,” he added.

In addition, the government has shown a proactive stance in facilitating regional aviation, even though the ecosystem remains at an early stage.

Despite serving different market segments, Dassault and ATR identify similar challenges when engaging with Vietnam. For Dassault, the main hurdle is familiarity. “In emerging markets, companies may be unfamiliar with aircraft ownership, operating costs and maintenance obligations,” Brana said, noting parallels with China’s early business aviation market.

ATR, meanwhile, points to competition for attention. With airlines focused on wide-body orders and international expansion, regional opportunities can be overlooked. “The key is finding entrepreneurs willing to build dedicated regional airlines,” Clercin said. “Regional aviation requires a different mindset.”

From a policy perspective in Vietnam, the revised Law on Civil Aviation, set to take effect in 2026, is expected to create a more enabling legal framework, widening the scope for private-sector participation in investment, operations and the development of aviation infrastructure.

Vietnam’s business aviation market has grown quickly over the past decade. What are the main drivers behind this growth, and how mature is the market today?

Business aviation market will grow alongside wealth
Paul Desgrosseilliers

If business aviation is defined strictly, Vietnam’s market is actually very young. Meaningful growth has really only started in the last 3-4 years. Before the pandemic period, there were effectively no business jets based in Vietnam. Coming out of the pandemic, companies and individuals began operating their own aircraft, initially through charter and later through managed ownership.

Today, the market stands at just under a dozen business jets, around 10-12 aircraft, with at least 3-4 more expected to enter service this year. From a numerical standpoint, the base is still small, but the growth rate is very high.

Vietnam’s economy is growing rapidly across manufacturing, real estate, industrial development and services. Frequent visits to both Hanoi and Ho Chi Minh City make this growth very visible, from large-scale construction to expanding industrial zones. As wealth increases among corporations and individuals, international business activity grows as well.

Vietnamese companies are no longer operating within domestic or regional markets. Many are deeply integrated into global supply chains, with frequent travel to China, Southeast Asia, the Middle East, Europe and North America. Business aviation supports this international reach by providing flexibility, efficiency and access to destinations that are not well served by commercial airlines.

In more mature markets such as North America, around 90 per cent of business jet utilisation is business-related rather than leisure-driven. Vietnam is following a similar pattern.

ExecuJet has obtained certification in Vietnam and now provides local maintenance support. What services are currently offered?

Vietnam has a unique regulatory environment compared with many other Southeast Asian markets. All aircraft owned and operated in Vietnam must be registered locally. Foreign-registered aircraft are not permitted to operate domestically. As a result, maintenance providers must hold Vietnamese regulatory approval in order to support these aircraft.

Recognising this requirement, ExecuJet began working with Vietnamese authorities more than a year ago to obtain the necessary approvals. The certification process was completed around six months ago, allowing the company to provide maintenance services for Vietnamese-registered business jets.

Vietnam was among the first Southeast Asian markets ExecuJet entered. Why was Vietnam prioritised?

Several factors influenced the decision. Firstly, the expansion began with an existing customer relationship. Initial interest came directly from Vietnamese operators seeking maintenance support.

Secondly, the aircraft types operating in Vietnam align closely with ExecuJet’s existing capabilities. The company already serves as an authorised service centre for Gulfstream and Dassault aircraft, which dominate the Vietnamese fleet.

Thirdly, geographic proximity played an important role. Hanoi, for example, is only around three hours by air from Beijing. From a customer perspective, flying to China for maintenance does not significantly increase travel time compared with other regional options.

Business aviation growth has been uneven across Southeast Asia. How does Vietnam compare with other regional markets?

Vietnam’s market remains smaller than more mature regional peers, but its growth trajectory is strong. Singapore, for example, had only a handful of business jets 15 years ago. Today, the fleet exceeds 80 aircraft. Indonesia operates around 60 business jets, while Thailand has approximately 45.

Vietnam’s fleet of around 12 aircraft represents a significant jump from zero just a few years ago. Importantly, multiple additional deliveries are already planned, indicating confidence in long-term growth.

Each market has its own characteristics. Aircraft preferences differ based on geography, business needs and infrastructure. Some markets favour smaller aircraft, while others gravitate toward large-cabin jets. Despite these differences, the underlying trend across Southeast Asia is consistent: economic growth is driving increased demand for business aviation.

ExecuJet Haite is based in China. What challenges arise when supporting Vietnam from abroad, and how are they addressed?

In the long term, there is strong interest in developing infrastructure within Vietnam, including business jet maintenance, repair, and overhaul (MRO) and fixed-base operator (FBO) facilities.

However, the current fleet size does not yet justify major investment. Typically, a base of 30-40 aircraft is needed to support standalone infrastructure economically.

Vietnam’s airport development plans may change this equation. Several new airports are under construction or planned, and business aviation zones are expected to be incorporated. FBOs are likely to be established first, with MRO facilities following as the fleet expands. When the infrastructure matures, opportunities for deeper local engagement will emerge. Until then, proximity to China allows efficient cross-border support without compromising service quality.

Sun PhuQuoc Airways secures AJW Group support for fleet operations

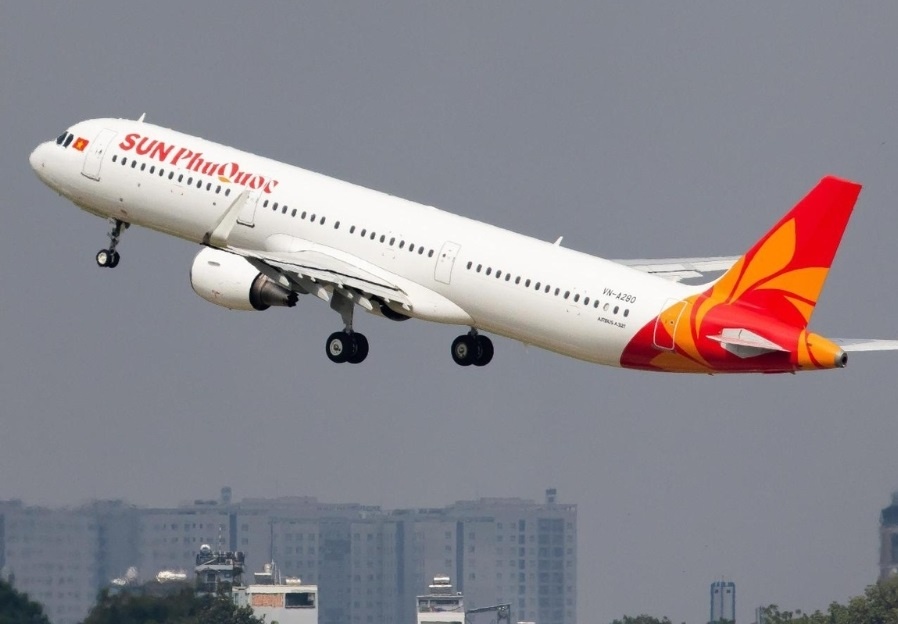
Sun PhuQuoc Airways and UK-headquartered AJW Group signed an agreement on February 4 under which AJW will provide comprehensive support, including maintenance services and spare parts supply, for the airline’s fleet of six aircraft, comprising two A321ceos and four A321neos. The partnership is expected to strengthen operational readiness and support planned network expansion.

AJW Group is an independent provider of component, repair, and supply chain solutions for commercial and business aviation, supporting more than 1,000 airlines across over 100 countries.

Sun PhuQuoc Airways is a startup carrier partly owned by Sun Group, a Vietnam-based developer and hospitality group. The airline currently operates a fleet of Airbus A321ceo and A321neo aircraft, initially connecting Phu Quoc Island with Ho Chi Minh City, Hanoi, and Danang. The carrier plans to expand routes to South Korea and Taiwan from 2026.

The airline is expected to expand its fleet rapidly in the coming years, supported by the financial backing and strategic experience of the Sun Group, adding significant momentum to its development in the region.

Scott Symington, chief commercial officer at AJW Group, commented, said, “We are delighted to support Sun PhuQuoc as they launch operations and grow their network, and we look forward to building a long-term partnership.”

Pham Dang Thanh, deputy CEO at Sun PhuQuoc Airways, added, “As a new airline, it was important for us to select a partner that understands both our immediate operational needs and our long-term growth ambitions. AJW Group demonstrated strong technical capability, and flexibility, and we are pleased to have them supporting our A320 fleet as we launch and grow our network.”

Aviation industry anticipates upcoming growth period Aviation industry anticipates upcoming growth period

Driving on growth momentum, air carriers in Vietnam are leaning into new plans to anticipate the next growth phase.

Sun PhuQuoc Airways cleared for commercial flights Sun PhuQuoc Airways cleared for commercial flights

Sun PhuQuoc Airways, backed by Sun Group, has secured regulatory approval to operate commercial flights, paving the way for the airline’s entry into Vietnam’s aviation market.

Hermes joins Long Thanh cargo terminal development Hermes joins Long Thanh cargo terminal development

Hermes Logistics Technologies has joined the development of Long Thanh International Airport’s new cargo terminal, marking a major step in applying advanced air cargo management solutions to Vietnam’s aviation infrastructure.