On July 17, the Vietnam Pepper and Spice Association (VPSA) submitted an official petition to the Ministry of Agriculture and Environment (MoAE) over the slow issuance of food safety certificates for plant-based exports, especially spices, under Circular No.12/2025/TT-BNNMT.

EU regulations stall pepper exports

Since July 1, certification responsibility has shifted to provincial-level authorities. However, the new rules fail to fully inherit the procedures outlined in Circular No.44/2018, creating confusion and delays in certificate processing.

“Spice exporters are facing serious obstacles in securing certifications required by key markets, particularly the EU,” the VPSA noted in a formal request. “The bottleneck has stalled exports, disrupted supply chains, and eroded trust with international partners.”

The association called on the MoAE to urgently resolve administrative bottlenecks, revise the circular to align with international requirements, and implement immediate training for local authorities and exporters to streamline procedures.

In the short term, VPSA estimates that nearly 250 tonnes of pepper are being held back due to certification delays, threatening existing contracts and adding storage and logistics costs.

This issue mirrors similar challenges faced by fruit and vegetable exporters earlier this month, who were unable to ship goods like dragon fruit, chilli, and okra to Europe for the same reason.

According to the MoAE, Vietnam exported around 25,000 tonnes of pepper in June, valued at $169.2 million. In the first half of the year, total exports reached nearly 125,000 tonnes, worth $859.6 million, down 12.4 per cent in volume but up 35.7 per cent in value on-year.

EU court rejects TikTok challenge against new EU digital rules EU court rejects TikTok challenge against new EU digital rules
Australian plums hit Vietnamese market Australian plums hit Vietnamese market
Vietnamese coconut exports to China climb Vietnamese coconut exports to China climb
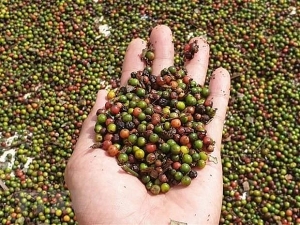
Vietnam pepper exports reclaim billion-dollar mark after a decade Vietnam pepper exports reclaim billion-dollar mark after a decade
Agriculture exports under impacts of US, EU tariffs Agriculture exports under impacts of US, EU tariffs

The festival was a long-cherished idea aimed at boosting trade promotion and business matchmaking for the fruit and vegetable sector.

The inaugural Vietnam Fruit and Vegetable Festival 2025 was held in Singapore on July 18,  with the Vietnam Trade Office in Singapore acting as the host, in partnership with the Singapore Fruits and Vegetables Importers and Exporters Association (SFVIEA).

Mr. Cao Xuan Thang, Trade Counselor and Head of the Vietnam Trade Office in Singapore, was quoted by the Vietnam News Agency as  stating at the event that the festival was a long-cherished idea aimed at boosting trade promotion and business matchmaking for the fruit and vegetable sector.

He noted that Singapore serves as a critical transshipment hub. By strengthening the presence of Vietnamese goods with international partners in the city-state, Vietnamese enterprises can leverage Singapore as a gateway to penetrate other regional markets.

The festival created numerous opportunities for trade and networking between Singaporean partners and Vietnamese businesses. Featured items included durian, Hoa Loc and Cat Chu mangoes, lychee, longan, coconut, dragon fruit, bananas, pomelo, various mushrooms, taro, and an assortment of vegetables and spices.

Vietnamese Ambassador to Singapore Tran Phuoc Anh, also quoted by the news agency, described the collaboration as a highly beneficial initiative for promoting bilateral trade. He said that fruits and vegetables were chosen as the initial focus due to the sector’s immense potential.

“With our strengths in diverse, fresh, high-quality products at prices suitable for the Singaporean market, we have identified this as a spearhead sector to penetrate Singapore and, from there, expand to other regions,” the ambassador said.

Meanwhile, Mr. Tai Seng Yee, Vice Chairman of the SFVIEA, emphasized that Singapore is a highly competitive market.

 “It is therefore excellent that Vietnam is supplying a greater variety of high-quality fruits and vegetables here,” he said, as quoted by the news agency. He also highlighted Singapore’s role as a highly efficient logistics hub, capable of facilitating the re-export of Vietnamese produce to other markets.

Throughout the festival, the Vietnam Trade Office showcased the nation’s agricultural advantages, particularly the diversity of its specialty crops, consistent quality, and competitive pricing, which are considered key strengths of its fruit and vegetable industry.

The event also served as a platform to promote Vietnam’s traditional culinary culture and provided an invaluable opportunity for Vietnamese enterprises to connect directly with a wide range of international partners in Singapore, including supermarket chains, industry associations, chambers of commerce, hotel groups, and wholesale and retail businesses.

Total investment capital estimated at $638 million.

The People’s Council of northern Thai Nguyen province has approved a project to build the Hanoi – Thai Nguyen – Cho Moi expressway under the Public – Private – Partnership (PPP) model.

The 100.69-km expressway will start from the intersection of the Ring Road No.3 in Hanoi and end at the Thanh Binh intersection in Cho Moi commune in  former Bác Kan province (now Thai Nguyen).

Total investment capital is estimated at VND16.789 trillion ($638 million). Of which, over VND5.3 trillion ($201 million) will be funded from the State budget.

The project consists of two sections. The first section is 61.2km long,  lasting from Hanoi to Thai Nguyen. It will have six lanes, allowing a maximum speed of 100 kph. The second, lasting from Thai Nguyen to Cho Moi commune, will have four lanes and allowing a maximum speed of 100 kph.


HONG KONG SAR – Media OutReach Newswire – 16 July 2025 – MSIG Insurance (Hong Kong) Limited (“MSIG”) today published its sixth annual MSIG Claims Report which presents the total claims honoured in Hong Kong and Macau during the year as well as the insurer’s latest initiatives. In 2024, MSIG’s claims settlement ratio reached 94.5% – rising for the third consecutive year, up from 92.4% in 2021.

The insurer honoured claims totalling HK$347,983,977 in Hong Kong and Macau, while receiving just 9 complaints throughout the year (down from 13 in 2023 and 50 in 2020). 2024 was also the first year that two categories – Employees’ Compensation Hong Kong and Marine – achieved 100% settlement ratios, a significant milestone that reinforces why the insurer has grown as a trusted partner. Helper (99.17%) and Personal Accident (96.85%) followed as the next highest categories.
In 2024, MSIG put even more emphasis on quick response and rapid claims processing. This led to significant compliments from customers and wide-ranging examples of how the insurer responds to incidents with fast, intuitive processes that help those affected to move forward.
Philip Kent, Chief Executive Officer of MSIG Hong Kong, said: “Every year brings new challenges, and 2024 was no different. Our teams have worked exceptionally hard to ensure that our service to customers remains at the fore, because we know that every claim is personal. By making the claims process faster and easier, we aim to help each of our customers move forward with assurance that they will receive the financial compensation they are owed. Innovation is at the heart of this, and our teams should be proud of the industry recognition they have received for their efforts. I have every confidence that we will continue to go from strength to strength in providing sincere customer service backed by leading digital capabilities – all part of our commitment to supporting our customers at every phase of their lives.”
MSIG’s focus on claims excellence has led to notable industry recognition in 2024, including:

  • Second consecutive year as a Top 3 Finalist in the category of “Outstanding Claims Management Award – General Insurance” – Hong Kong Insurance Awards 2024

  • Winner of “Claims Initiative of the Year” – InsuranceAsia News Awards for Excellence 2024

Setting the service standard in digital claims
Following the launch of Zero Touch, a digital solution for claims assessment that streamlines verification of customers’ claims history, policy validity and claims payment amounts, in the second half of 2023, the project has reported exceptional gains in efficiency. For Helper Insurance claims specifically:

  • Claims processing times have been reduced from 3-5 days to as little as 15 minutes for eligible clinical and dental claims.

  • Almost 75% of Helper claims are now automated, saving claims specialists some 200+ working days annually.

  • Simple claims do not require manual intervention anymore, increasing the focus on value-added services.

Building on this success, MSIG intends to further extend Zero Touch to cover its medical products in the future.
Innovating for the future
In 2024 and early 2025, MSIG introduced a suite of new services to support customers at every step:

  • MSIG Easy Lounge Service: Complimentary airport lounge access for travel insurance customers experiencing delays over 60 minutes, available at 1,600+ airports worldwide.

  • Claims Status Enquiry Page: 24/7 online claims tracking for peace of mind.

  • Day Case Endoscopy Programme: Cashless, convenient endoscopy arrangements for medical insurance customers.

  • Door-to-door Luggage Repair Service: Free pickup and delivery for travel-damaged luggage.

  • Overseas Medical Teleconsultation: Free telemedicine services for travel insurance customers travelling in Japan, Singapore, Thailand, Vietnam, and the Philippines.

Also reflecting MSIG’s overarching emphasis on extraordinary customer service and claims management was its inaugural “Serving with Heart, Putting You above All” branding campaign. Featuring videos of common insurance scenarios, the insurer partnered with Key Opinion Leaders to convey how a simple, intuitive claims experience can result in needed assurance during unexpected incidents.

The issuer is solely responsible for the content of this announcement.

Mr. Jimmy Koh, Head of Network Partnerships and Strategic Marketing, Group FDI Advisory, United Overseas Bank (UOB), shares his insights on why Vietnam remains on investors’ radar and UOB’s long-term commitment with a new headquarters building in Ho Chi Minh City.

We’ve heard the phrase “China Plus One” mentioned during the ASEAN Conference 2025. From your perspective, how has that concept evolved?

The concept of “China Plus One” has been around for quite some time and Vietnam was that “one.” That’s why Vietnam became so significant. Many large corporations, including major banks like UOB, established a strong presence in Vietnam early on. There was already a deep trust in Vietnam’s stability and environment.

But today, it’s no longer just “China Plus One.” It’s “China Plus Plus Plus Plus… Vietnam.” Businesses aren’t just looking for one alternative location — they’re diversifying across multiple countries. Some say, “We can’t put everything in Vietnam,” so they add other locations like Malaysia.

Now, it’s no longer about country-level diversification alone. It’s about industrial corridors. In Vietnam, that might mean Ho Chi Minh City, Hanoi, the VSIP zones, and other industrial clusters. In Malaysia, it’s Johor, Penang, or Sarawak. So you’re seeing a full ecosystem developing across regions not just countries.

But this is just the beginning. Change is constant, and we’re going to see even more transformation going forward. We’re always looking for the next shift and that, in my view, is crucial.

What about the global economy and de-risking policies? Do you think de-risking is driving real business decisions in Asia?

There’s a very interesting perspective I heard recently that the global economy is now in a “de-risking era.” If you trace this back, the world since World War II has been driven by Americans taking the lead. And the rest of the countries all follow the way the American works..

Whether it’s trade rules, capital market flows, or regulatory frameworks, much of it has been defined by the United States. If you look at the global economic landscape today, the largest economy is the U.S., followed by China, then Europe (or Germany), and Japan.

Japan and Germany, for instance, emerged from World War II and were significantly rebuilt with American support. As a result, the American model of doing business was widely adopted.

A major turning point came when China joined the WTO. At that time, China made up just 2% of global GDP. Today, that figure is around 15%. That growth surprised the U.S. which still holds about 25% of global GDP and they began to push for a reset in global supply chains.

This shift has had a huge impact, particularly on ASEAN. Since around 2016 when anti-globalization sentiment began rising ASEAN has emerged as a strategic alternative. In terms of global FDI, ASEAN’s share rose from 6% in 2015 to 18% today. That’s a threefold increase. And we’re not talking about projected figures these are real flows, happening now.

How has ASEAN managed to maintain its economic appeal amid global uncertainties, especially the recent slowdown in China?

The slowdown in China is certainly being felt, but ASEAN has shown resilience through what I call a “cushioning effect” driven by the realignment of global supply chains. What sets ASEAN apart is its geopolitical neutrality and strong regional cooperation. Rather than taking sides, ASEAN remains committed to openness and collective stability under the “ASEAN Outlook,” positioning itself as a steady hub amid global uncertainty. That’s the region’s strength in a rapidly shifting world.

Last year, you described Vietnam as a “bright star” within ASEAN. What factors make Vietnam stand out in the eyes of foreign investors, especially in the current global context?

Vietnam has consistently attracted strong FDI over the past decade. Several factors contribute to this: a hardworking and well-educated labor force, a competitive cost structure, and a clear strategic position in the alternative supply chain. Labor remains affordable, and investors are increasingly viewing Vietnam as a reliable and efficient manufacturing base.

Do you believe Vietnam will continue to attract more foreign investment in the coming years?

Absolutely. Vietnam will remain on the radar of foreign investors.

Take VSIP the Vietnam Singapore Industrial Parks. Five years ago, there were just nine zones. Today, there are 18. That’s a huge jump. One key example is Nghe An, where we’re seeing rising FDI inflows and more companies setting up operations. It’s a strong indicator of investor confidence in Vietnam.

While no single country will dominate, Vietnam is set to capture a significant share alongside Indonesia and Malaysia. It’s all part of a broader diversification strategy. I see ASEAN as a whole benefiting from this trend, rather than individual countries competing in isolation.

Has UOB observed any shift in investor sentiment toward Vietnam in recent years?

Following the tariff-related announcements in April, we surveyed around 100 investors. About 90% said they had no intention of changing their plans in Southeast Asia, including Vietnam. That said, a more cautious tone has emerged. Investors are becoming increasingly prudent. Instead of purchasing land outright, they may choose to lease. Rather than investing $200 million at once, they might spread the investment over time.

Some are now considering contract manufacturing (OEM) as an initial step, instead of immediately establishing full production facilities. This is not a sign of withdrawal; it reflects a more risk-averse approach. However, we must be realistic—integrating new suppliers into global supply chains is a rigorous process for multinationals. It cannot happen overnight.

From your experience, what sectors are currently attracting the most FDI interest in Vietnam and across ASEAN?

It depends on the country, but broadly speaking, there is strong investor interest in green energy, digital infrastructure, and fintech. If you look at what is shifting out of China, it is often labor-intensive manufacturing, consumer goods, and certain segments of technology that require geographic diversification. That said, not everything can move out of China. Take electric vehicles (EVs) as an example. Even if the assembly is relocated to Thailand, the core engine components still come from China.

The Vietnamese government has made notable policy shifts toward a green transition. What’s your view on Vietnam’s green ambitions?

“Going green” is an essential part of the journey for every economy. However, for emerging markets, it will take time. Take Indonesia as an example: about 70% of its power supply still comes from fossil fuels. That cannot change overnight. At UOB, we advocate for a just transition, one that balances environmental goals with economic development and livelihoods. It is about creating opportunities and sustainable growth while ensuring that no one is left behind.

As a developing market, where do you see untapped potential for FDI inflows into Vietnam?

Vietnam is still very much in an active FDI attraction phase. Many sectors that are drawing investment today have not yet reached their full potential. Manufacturing remains strong, particularly in electronics, E&E, TMT (technology, media, and telecommunications), and the consumer sector.

Interestingly, we continue to see significant interest from Taiwanese and Chinese investors. Textile is one of the big advantages of Vietnam. While some may consider textiles low-value, Vietnam’s strength in this area is unique. Whenever global supply chain leaders talk about textile production, Vietnam is always part of the conversation.

How is UOB’s FDI Advisory team supporting businesses entering the Vietnamese market?

At UOB, our role goes beyond banking. Our FDI Advisory team works closely with corporates to help them navigate new markets, especially in Vietnam. We connect them to government agencies, explain local regulations, and advise on incentives such as grants or local content requirements, including how to meet rules of origin in export markets.

We also introduce investors to trade associations to help integrate them into local supply chains and connect them with professional services in legal, human resources, and accounting. One challenge many Chinese companies face upon arriving in Vietnam is language, so having the right HR support is crucial. We help them understand how to work with local talent and comply with Vietnamese labor laws.

Our team also guides them through the regulatory complexity of ASEAN by assisting with licensing, clarifying market-specific policies, and fostering cultural alignment. These are essential steps for a smooth market entry and long-term success.

UOB recently announced the plan to build its new headquarters building in Ho Chi Minh City, Vietnam. Could you share the rationale behind this move?

Yes, that is a move that signals our long-term commitment. While most banks view real estate as a non-core asset, we see it differently.

In Chinese culture, there is a saying: “Even if the monk leaves, the temple remains.” Owning a building shows our clients that we are here to stay. It gives them confidence that UOB is not just entering the market opportunistically but is truly committed to supporting Vietnam’s economic development for the long term.

Our physical presence in places like Singapore, Malaysia, Thailand, Indonesia, China, and Vietnam reflects our investment in building long-term partnerships. That is the difference in how we operate.

This year marks 60 years of Singapore–Vietnam diplomatic relations. How is UOB, as a Singapore-based institution, contributing to stronger bilateral and ASEAN connectivity?

UOB has been present in Vietnam for 32 years. I still remember celebrating that milestone not long ago. Singapore and Vietnam marked 50 years of diplomatic ties two years ago, and now Singapore is celebrating its SG60 while UOB is marking its 90th anniversary.

These milestones reaffirm our commitment not only to Vietnam but also to the ASEAN region as a whole. We are not just looking at UOB at 90; we are planning for UOB at 100. Similarly, we are not only celebrating the past 60 years of Singapore; we are focused on how we can strengthen the next 40 years of economic and social connectivity.

We recently invested in building a new headquarters building here and took over Citi’s retail franchise in Vietnam. That speaks volumes about our intention to grow alongside Vietnam’s economy, its people, and its communities.
The gathering highlights Vietnam’s commitment to sharing its successful experiences and fostering a global platform for cooperation in rural and agricultural development.

Vietnam, in partnership with the Food and Agriculture Organization of the United Nations (FAO), hosted a high-level inter-regional forum on the “One Commune One Product” (OCOP) model on July 15.

The event brought together agriculture ministers and senior officials from 17 nations across Asia and Africa, including Bhutan, Nepal, Tunisia, Zambia, Zimbabwe, Ghana, Ethiopia, Cameroon, Mozambique, Sierra Leone, Côte d’Ivoire, Gabon, the Democratic Republic of the Congo, Malawi, Lesotho, South Sudan, and host country Vietnam.

As the first large-scale international forum on OCOP held among developing nations, the gathering highlights Vietnam’s commitment to sharing its successful experiences and fostering a global platform for cooperation in rural and agricultural development.

In his opening remarks, Mr. Tran Thanh Nam, Vietnam’s Deputy Minister of Agriculture and Environment, emphasized the forum’s significance, saying that “This event helps align global and regional efforts to implement the OCOP program, aiming to achieve the FAO’s ‘Four Betters’ initiative: Better Production, Better Nutrition, a Better Environment, and a Better Life.”

Launched by the Vietnamese Government in 2018, the OCOP program has been rolled out nationwide to drive rural economic growth by leveraging local strengths and unique regional advantages. More than just a product brand, OCOP is a comprehensive development model that integrates the government, private enterprises, cooperatives, and farmers. It focuses on capacity building, quality control, brand development, and market access for rural products.

“As of June 2025, Vietnam has certified 16,855 OCOP products at three stars or higher,” Mr. Nguyen Do Anh Tuan, Director General of the Department of International Cooperation at the Ministry of Agriculture and Environment, stated, adding that over 60% of OCOP-participating entities have reported an average annual revenue growth of 18%.

Ms. Beth Bechdol, Deputy Director-General of the FAO, described the initiative not only as a driver for local economic development but also as a cornerstone for sustainable agricultural growth. She highlighted that diversifying products, building resilience, and promoting knowledge sharing among nations are key for Asia and Africa to “act together and move forward together”.

“Vietnam is emerging as a ‘knowledge hub’ for rural development based on indigenous values and global connectivity,” Ms. Bechdol remarked. “Vietnam’s practical success in brand building, quality control, and developing unique rural products is a testament to its ability to transform small-scale production into sustainable value chains.”

Through its “One Country One Priority Product” initiative—the global counterpart to OCOP—the FAO is currently supporting the development of 56 special agricultural products worldwide. The initiative aims to harness local cultural values, improve livelihoods for rural populations, and promote a transparent, green, and sustainable food production ecosystem.

At the forum, Deputy Minister Tran Thanh Nam proposed establishing a network for South-South countries to share policies, technologies, and market information. He also recommended piloting a Public-Private-Community Partnership model to mobilize financial, technical, and indigenous knowledge for sustainable rural development. Notably, Vietnam emphasized the importance of empowering vulnerable groups—such as women, the elderly, people with disabilities, and ethnic minority communities—through the OCOP program.

Remittances from Africa record the higest increase of 130.8%.

Remittances to Ho Chi Minh City reached over $5.23 billion in the first six months of the year, according to the State Bank of Vietnam’s Region 2 Branch.

In the second quarter, the remittances to the city is estimated at nearly $2.82 billion, up 16.9% compared to the first quarter and 22.1% against the same period last year.

Remittances to the city from Africa in the six-month period recorded the highest increase of 130.8% year-on-year. It was followed by Asia with 16%, and America 11.9%.

Last year, total remittances to Ho Chi Minh amounted to over $9.54 billion. Of the total, remittances from Asia and America accounted for the largest share with 82.2%.


From July 1, a flat 2 per cent registration fee for new motorcycles has come into effect nationwide, replacing the previous 5 per cent rate that applied in major urban centres such as Hanoi and Ho Chi Minh City.

Vehicle fee structure aims for fairness for localities
Vehicle fee structure aims for fairness for localities, illustration photo/VNA

The policy aims to harmonise tax obligations across regions and create more equitable conditions for vehicle ownership.

The reduction offers significant cost savings for consumers. A standard Honda Lead scooter, priced at VND40 million (around $1,600), previously incurred a registration fee of $80 in big cities. Under the new policy, the fee drops to just $32.

For high-end models like the Honda Gold Wing, which retails at around $49,200, the fee is reduced from $2,450 to $980. Even entry-level models such as the Wave Alpha 110, priced at around $710, now carries a fee of $14, down from over $35.

Used motorcycles remain subject to a 1 per cent registration fee from the second transaction onward, consistent with previous regulations.

According to the Ministry of Finance (MoF), the move responds to recent administrative restructuring, which involved merging communes and districts nationwide.

“The unified fee structure ensures fairness for residents in newly consolidated localities, preventing them from being subject to higher rates based on their previous administrative designation,” the MoF noted in its statement.

Importantly, the decree also decentralises the authority to issue vehicle valuation tables from the MoF to provincial people’s committees. This measure is designed to enhance administrative efficiency and allow local governments to adapt more responsively to market conditions and regional dynamics.

The revised fee schedule also includes other vehicle types. Four-wheeled electric buggies used in golf courses and resorts, as well as specialised utility vehicles, are now subject to a 2 per cent fee. Passenger pickup trucks face a 10 per cent rate, similar to regular passenger cars.

Double-cabin pickups and cargo vans with two or more rows of seats and a fixed partition separating passenger and cargo areas will be taxed at 60 per cent of the standard car registration fee.

Industry stakeholders seem to have responded positively. “This is a practical, demand-driven policy that lowers the upfront barrier for consumers,” said Nguyen Van Hieu, sales director at a Hanoi-based motorcycle dealership. “We expect to see stronger purchasing activity from July onwards, especially among first-time buyers and customers who had previously delayed purchases due to high fees.”

Vietnam’s motorcycle market, which had endured a downturn during 2022–2023, has shown clear signs of recovery in 2025. According to industry estimates, over 1.32 million units were sold nationwide as of the end of May, marking a more than 20 per cent increase on-year. The growth is particularly robust in the electric scooter segment, where affordability, fuel savings, and ease of use continue to draw in younger urban consumers.

Tax experts also view the reform as a positive development in Vietnam’s broader fiscal restructuring.

“By simplifying the registration fee system and empowering local authorities, the government is easing the burden on both taxpayers and tax administrators,” said Tran Thi Hoai An, an independent tax researcher based in Ho Chi Minh City. “This aligns with ongoing efforts to decentralise public finance and make tax policies more adaptive.”

The call came during the Prime Minister’s meeting with Mr. Gerald Toledano, FTSE Russell’s Global Head of Equity and Multi-Asset, who is leading a delegation to assess Vietnam’s capital markets for a potential reclassification.

Prime Minister Pham Minh Chinh has urged global index provider FTSE Russell to accelerate its support for Vietnam’s bid to achieve emerging market status, stressing the need for a transparent and stable market to drive capital mobilization.

The call came during the Prime Minister’s meeting in Hanoi on July 17 with Mr. Gerald Toledano, FTSE Russell’s Global Head of Equity and Multi-Asset, who is leading a delegation to assess Vietnam’s capital markets for a potential reclassification, according to a report from the Government News.

The Prime Minister specifically requested FTSE Russell’s advisory support on strengthening the legal framework, modernizing infrastructure, implementing smart governance, and developing a high-caliber workforce. He also asked for assistance in attracting global capital flows and realizing Vietnam’s ambition to establish an international financial center.

In response, Mr. Toledano affirmed FTSE Russell’s firm commitment to supporting Vietnam’s push to upgrade its stock market from “frontier” to “emerging”. He pledged to partner with the nation on its long-term development goals, including its Vision to 2045 for economic prosperity, and committed to actively sharing information about Vietnam’s reforms and progress with the global investment community.

Mr. Toledano highlighted the impressive results of Vietnam’s market development, noting its stock market now boasts the highest liquidity in the ASEAN region, surpassing both Thailand and Singapore.

He praised Vietnam’s determination and credited critical reforms—such as developing a roadmap for a Central Counterparty (CCP) mechanism—as key factors positioning the economy for sustainable growth and supporting its case for reclassification.


Vietnam has rolled out many efforts to soon meet upgrading requirements.

With Vietnam’s reform determination together with support from international organizations, its stock market will soon meet requirements for upgrading and becoming an attractive destination in the region,  Minister of Finance Nguyen Van Thang told Gerald Toledano, Global Head of Equity and Multi Asset of FTSE Russell, a member of the London Stock Exchange Group, during their working session in Hanoi on July 17.

Mr. Thang outlined Vietnam’s ongoing reforms, noting that the Ministry of Finance has directed the State Securities Commission of Vietnam (SSC) to engage regularly with international market rating agencies and investors to share updates on Vietnam’s stock market reforms and gather feedback.

The ministry is finalizing a draft decree amending the Government’s Decree No. 155/2020/ND-CP to enhance transparency in foreign ownership limits and eliminate outdated rules, such as those allowing shareholder meetings to set maximum foreign ownership levels, he said.

Regarding administrative procedures relating to investment activities of foreign investors, the ministry has coordinated with the State Bank of Vietnam (SBV) to simplify procedures and cut processing time, according to the minister.

On the foreign exchange market, he said the ministry is working with the SBV to develop a legal framework for hedging instruments to address exchange rate risks.

Concerning the central counterparty (CCP) clearing mechanism, Vietnam has recently launched KRX system, laying technical groundwork for the launch of the CCP in early 2027.

For his part, Mr. Toledano affirmed that FTSE Russell stands ready to help Vietnam upgrade its capital market infrastructure to attract stronger inflows of foreign investment. It will also help the SBV develop indices that help investors better manage financial risks.